Growing Without Collapsing: What's Pressuring Logistics in Mexico?
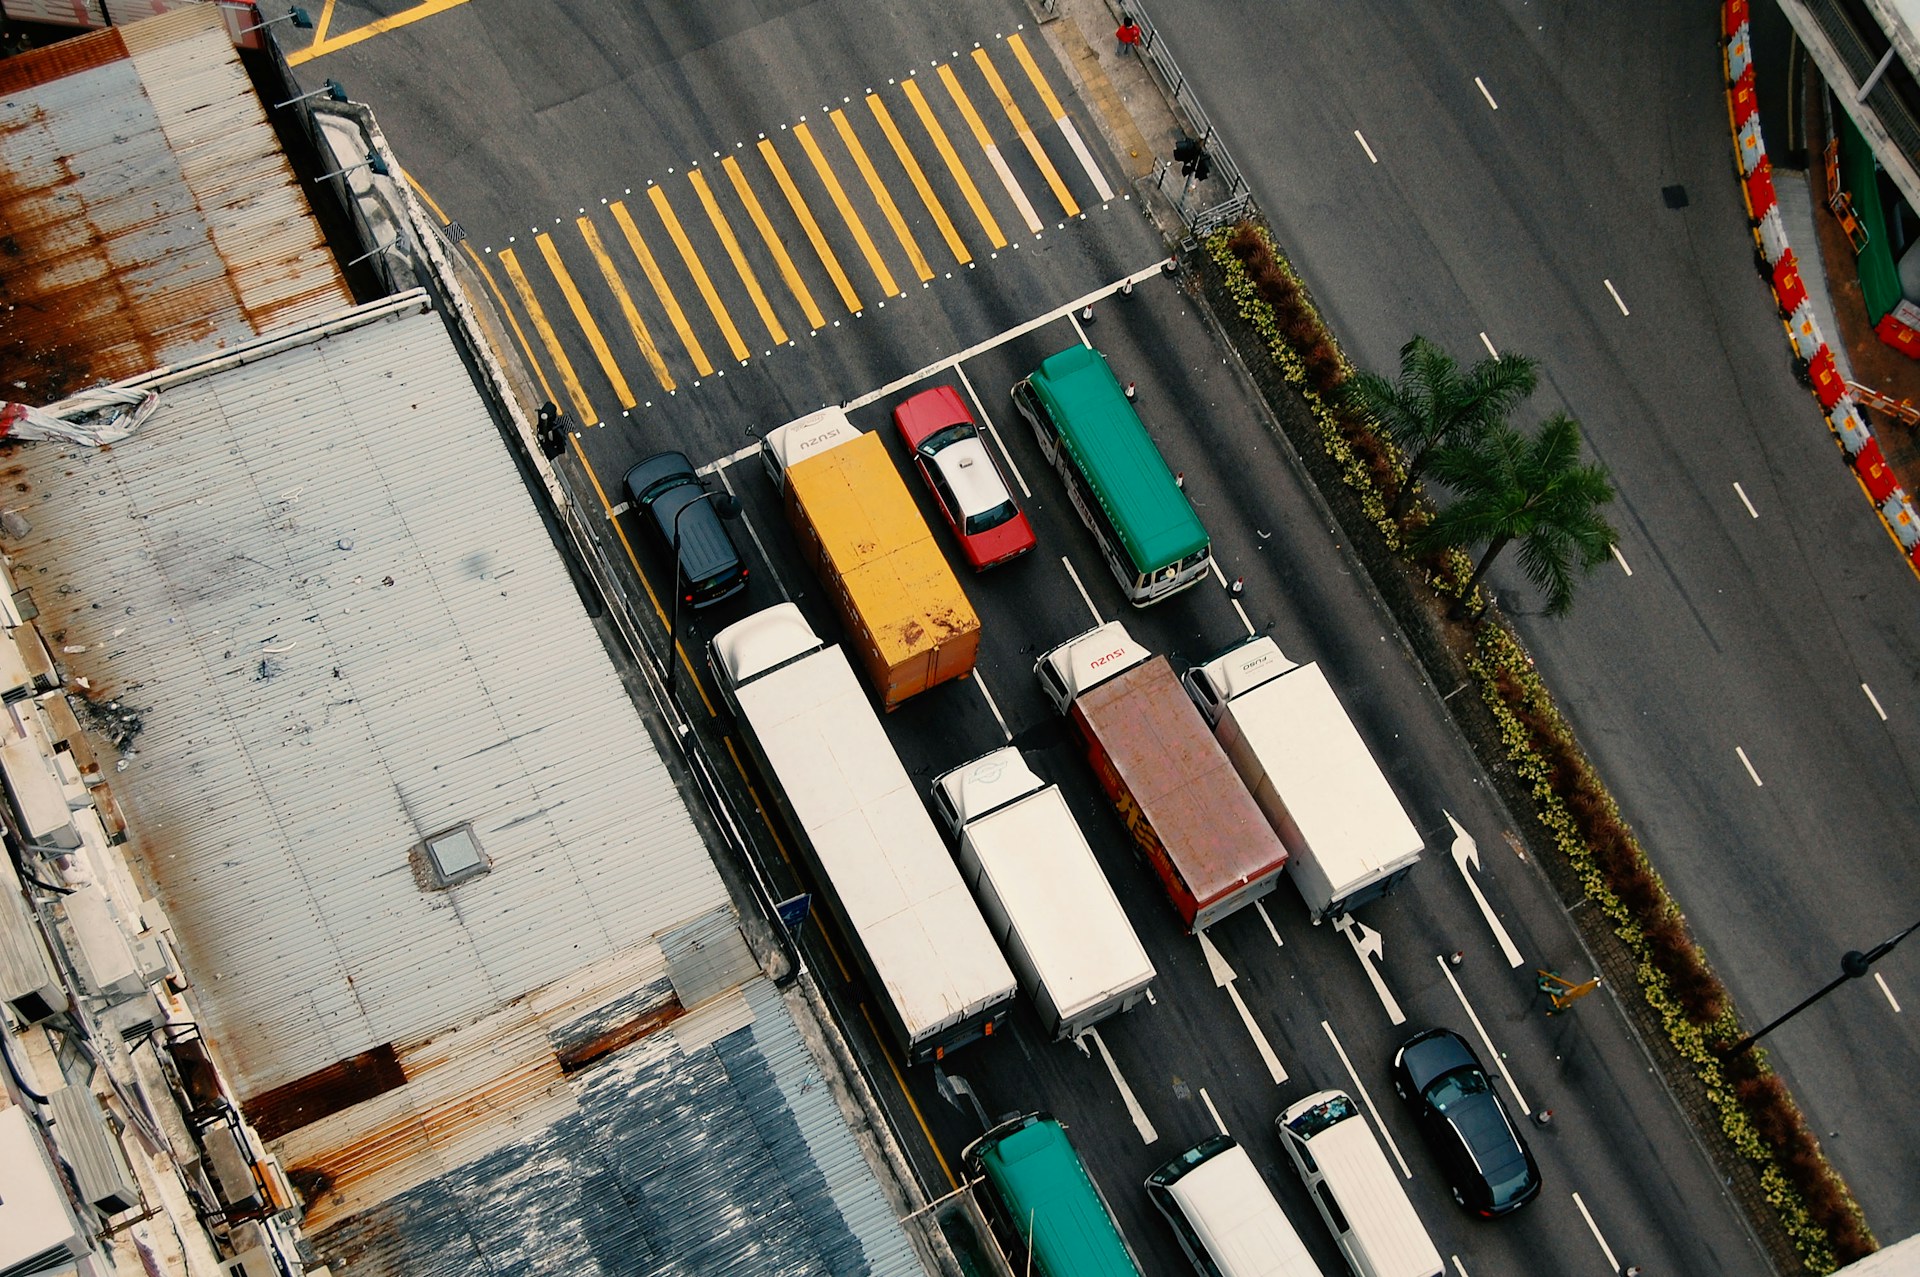
An analysis of the challenges and pressures facing Mexico's logistics sector, impacting business growth and supply chain efficiency.
Logistics in Mexico is no longer just an operational function focused solely on cost reduction. Today, it underpins sales, protects profit margins, and determines whether a company can grow without its own supply chain becoming a bottleneck.
A manufacturing plant can increase its production in a matter of months. However, its suppliers, warehouses, transport units, and distribution centers do not always keep pace. When this network falls behind, growth transforms from an advantage into a constraint.
“Logistics is much more than cost: it’s agility, it’s flexibility, and it’s responsiveness in an increasingly uncertain market,” summarizes Eric Porras Musalem, Director of the Global Executive MBA at Egade Business School of Tecnológico de Monterrey. Furthermore, this pressure is reflected in business costs, warehouse utilization, demand for industrial spaces, port activity, and transportation service prices.
Logistics in Mexico Can Represent Up to 18% of Sales
The “4th National Study of Logistic Indicators” – prepared by #SoyLogístico Association, with the collaboration of LDM Empowering Your Supply Chain, Egade Business School, and the Ministry of Economy – analyzes information from over 160 companies and covers the years 2023, 2024, and 2025.
Its results show that total logistics costs represented, on average, the following percentages of participating companies’ sales:
- 18% in the
- 17% in construction.
- 15% in logistics services.
- 13% in manufacturing.
- 12% in food.
- 12% in retail.
- 11% in health and pharmaceuticals.
This data does not mean that all companies within an industry face the same cost. It does indicate that transporting, storing, distributing, and managing inventory can absorb a significant portion of revenue. The difference also depends on the type of merchandise and the complexity of each chain. The automotive industry, for example, moves high-volume vehicles, auto parts, and components, while other sectors may operate with products that are easier to consolidate.
An apparently efficient operation can lose profitability if it holds merchandise for too long, poorly utilizes available space, or duplicates movements to meet customer demands. Additionally, a more resilient supply chain often requires greater investment. Safety stock, alternative suppliers, additional capacity, and backup routes all come with a cost. For this reason, a business decision should involve calculating the cost of preventing an disruption versus the cost of halting operations.
Warehousing: Lower Occupancy Can Also Signal a New Strategy
The ENIL documented significant changes in warehouse utilization between 2024 and 2025. Utilization in construction dropped from 93% to 82%, an 11-percentage-point reduction. In food, it went from 91% to 82%; in automotive, from 93% to 88%; and in manufacturing, from 90% to 85%.
The study interprets this trend as a freeing up of operational space and an adjustment in inventory levels held within facilities. The reduction alone does not allow us to conclude that activity has decreased. It may also reflect a more flexible operation, lower saturation levels, or a review of installed capacity.
Outsourcing shows another transformation. Between 2024 and 2025, the use of third-party logistics providers for warehousing increased from 21% to 41% in food, from 11% to 24% in health and pharmaceuticals, and from 20% to 29% in manufacturing. The opposite occurred in automotive: outsourcing decreased from 56% to 38%. This difference reveals that there is no single, universal strategy. Some companies seek flexibility through specialized providers; others prefer to regain control over their facilities and processes.
E-commerce Has Made Delivery Part of the Product
E-commerce has shifted a significant portion of the competition to the consumer’s doorstep. The Mexican Online Sales Association (AMVO) reports that e-commerce in Mexico reached 941 billion pesos with 77.2 million digital buyers in its “2026 Online Sales Study.” The organization also notes that e-commerce is growing at a rate 25 times higher than GDP.
Each purchase adds tasks that the consumer rarely observes: order preparation, packaging, unit assignment, route selection, delivery, and, in some cases, returns. For the customer, it all boils down to one expectation: receiving the complete product quickly and on the promised date.
The last mile concentrates a significant portion of the complexity. In an interview, Porras Musalem stated that Mexico City, Monterrey, and Guadalajara face higher costs due to congestion, travel times, and lower productivity per unit. Puebla and Querétaro are also beginning to experience this pressure due to the growth of their residential, industrial, and commercial areas. The problem is not solely about covering more miles. Urban delivery can require more time, more fuel, more units, and greater coordination to move fewer packages per trip.
Industrial Hubs Grow 7%, but Warehouse Construction Falls 20%
According to Solili, demand for industrial space in Mexico totaled 945,000 square meters between July and August 2026, an annual increase of 7%. Mexico City accounted for 31% of the demand; Guadalajara and Monterrey each contributed 16%. Together, these three markets represented 63% of national demand during the two-month period.
Supply is advancing more cautiously. Industrial space under construction closed August at 3.7 million square meters, 20% less than a year prior. New projects initiated totaled 540,000 square meters, an annual reduction of 32%. Concurrently, availability reached 6.1 million square meters, with a vacancy rate of 5.3%. The difference between markets is significant: Tijuana registered 10% vacancy; Reynosa, 8.4%; Monterrey and Ciudad Juárez, 6.6%. In contrast, Aguascalientes reported 1.2% and Puebla, 1.9%.
The average industrial rent price reached $7.67 per square meter per month, 5% higher than in August 2025. These figures do not describe a uniformly saturated market. They indicate more demanding competition among locations. In some hubs, there is limited availability; in others, companies must carefully evaluate the warehouse, access routes, security, and services that can support their operations.
Guadalajara offers an example of this proactive approach. During the first quarter of 2026, the market registered 148,000 square meters of leasing, 68% more than a year prior. The El Salto corridor accounted for over 113,000 square meters, and Zapopan Norte for 21,000. Solili reported that some leases were finalized in properties that were still in the early stages of construction.
Routes and Ports Turn Distance into a Risk Variable
The challenge of moving goods is not solely related to transportation costs. It is also tied to the predictability of routes. As a structural reference, the SICT’s road diagnosis—with 2024 data incorporated into the 2025-2030 Sector Program—indicates that the country’s 15 main corridors total over 19,000 kilometers. Of this network, 61% of segments operate at service levels A or B; 20% are at level C, and 19% are at levels D, E, or F. These latter levels represent less favorable circulation conditions and a higher risk of variation in transit times. This data shows that almost one in five segments can become a point of tension for companies reliant on on-time deliveries, lean inventories, or cross-border supply chains.
The SICT also reported that 38 toll plazas, equivalent to 6% of the total, were experiencing some degree of saturation and required short-term expansion. Furthermore, average daily traffic on the toll road network increased by 45% between 2012 and 2024.
Ports are showing increasing demand. In Manzanillo, total cargo movement reached 16.3 million tons during the first half of 2026, 5.5% more than in the same period of 2025. Containerized cargo reached 11.4 million tons, with a 4.6% annual increase.
Logistics Services Also Face Price Increases
The Inegi’s “Producer Price Index” shows that the transportation, postal, and warehousing group increased by 4.90% annually in August 2026. Breaking down by services, producer prices registered the following increases:
- Freight rail transport: 7.55%.
- Port usage: 7.83%.
- General cargo road transport: 3.66%.
- Cargo warehousing: 2.44%.
- Parcel and courier services: 4.71%.
Efficiency Reduces Costs; Responsiveness Protects Sales
One of the core aspects of logistics is distinguishing between efficiency and service level. Efficiency relates to using fewer resources to achieve greater output. Service, on the other hand, involves delivering on time, fulfilling orders correctly, and responding when conditions change.
While a company may operate with low costs, it risks losing customers if it misses delivery deadlines. It can also offer rapid deliveries but compromise its profitability if it requires too many units, warehouses, or movements to sustain that promise.
Porras Musalem warns that plant growth must be accompanied by a review of inbound and outbound routes, the capacity of distribution centers, and the advisability of using private transportation versus contracting a 3PL (third-party logistics) provider. Operating a warehouse or distribution center at 100% capacity may seem efficient but reduces the margin for reaction to demand fluctuations. Technology can help forecast demand, detect anomalies, assign vehicles, and anticipate delays. However, the specialist maintains that companies must redesign their processes before automating them. Artificial intelligence can also improve real-time decision-making, although its more sophisticated adoption is still concentrated among companies with greater investment capacity. For small and medium-sized enterprises, the challenge lies in finding scalable solutions and demonstrating their return on investment.
Read More: https://www.liderempresarial.com/carga-especializada-crece-41-7-en-el-parque-vehicular-de-san-luis-potosi/
The entry
first appeared on Líder Empresarial.
More Articles
San Luis Potosí's Hybrid Vehicle Fleet Grows 56%, Leading Bajío Corridor
Sep 24, 2026
Capgemini Mexico Recognized on Most Ethical Companies Ranking 2026
Sep 24, 2026
Guadalajara-Paris: Dates, Frequencies, and Key Details of the New Flight
Sep 7, 2026
2027 Economic Package: Coparmex Jalisco's Proposal to Drive State Growth
Sep 8, 2026
Artificial Intelligence Concerns the Vatican: Pope Leo XIV's Stance
Sep 24, 2026
Sheinbaum in Querétaro: Train Projected for Completion in 2027
Sep 21, 2026