Deloitte: 2027 Tax Reform and Revenue Collection in Mexico
Deloitte experts analyze Mexico's 2027 tax reform, focusing on enhanced compliance and revenue generation strategies.
Deloitte: 2027 Tax Reform and Revenue Collection in Mexico
According to Abel Camacho Brito, Tax Controversy Partner at Deloitte, the Federal Government’s proposal does not aim to increase the tax burden through higher tax rates. Instead, its focus is on strengthening tax enforcement and compliance mechanisms to reduce tax evasion and avoidance practices, thereby enhancing the state’s revenue collection capacity.
The consultant states that the proposal includes three modifications aimed at immediately expanding the corporate income tax (ISR) base. These include a generalized limit on authorized deductions, a restriction on the amortization of prior year tax losses, and an adjustment to the calculation mechanics to increase provisional payments for organizations with accumulated income exceeding 50 million pesos that determine taxable income.
These measures integrate recent enforcement criteria, such as effective tax rates by sector of activity, into the operational structure of ISR. The central intention is to scrutinize economic units that report consecutive losses or exhibit a reduced effective tax rate on corporate income tax, based on the principle that operational continuity should reflect financial viability.
For companies, Camacho Brito notes that these changes will result in an increase in corporate ISR determination by establishing, in practice, a minimum tax payment. Given this outlook, it is essential for organizations to conduct financial modeling and impact projections for the coming years.
Furthermore, direct audits are expected to continue the upward trend observed in recent periods. In this environment, according to the specialist, strengthening internal controls and permanent preventive review are consolidating as the core management tools for companies and major taxpayers in the country.
Finally, regarding the expansion of the tax base and attention to informality, the proposal to raise the income threshold for tribute under the simplified tax regime (Resico) is analyzed. While this measure facilitates the inclusion of small taxpayers, it is considered insufficient to increase the captive taxpayer base and elevate revenue collection to OECD averages.
You might be interested in…
The entry
More Articles
Deloitte: 2027 Tax Reform and Revenue Collection in Mexico
Nov 1, 2026
Lula Wins Brazilian Elections: What is the Connection with Sheinbaum?
Oct 26, 2026
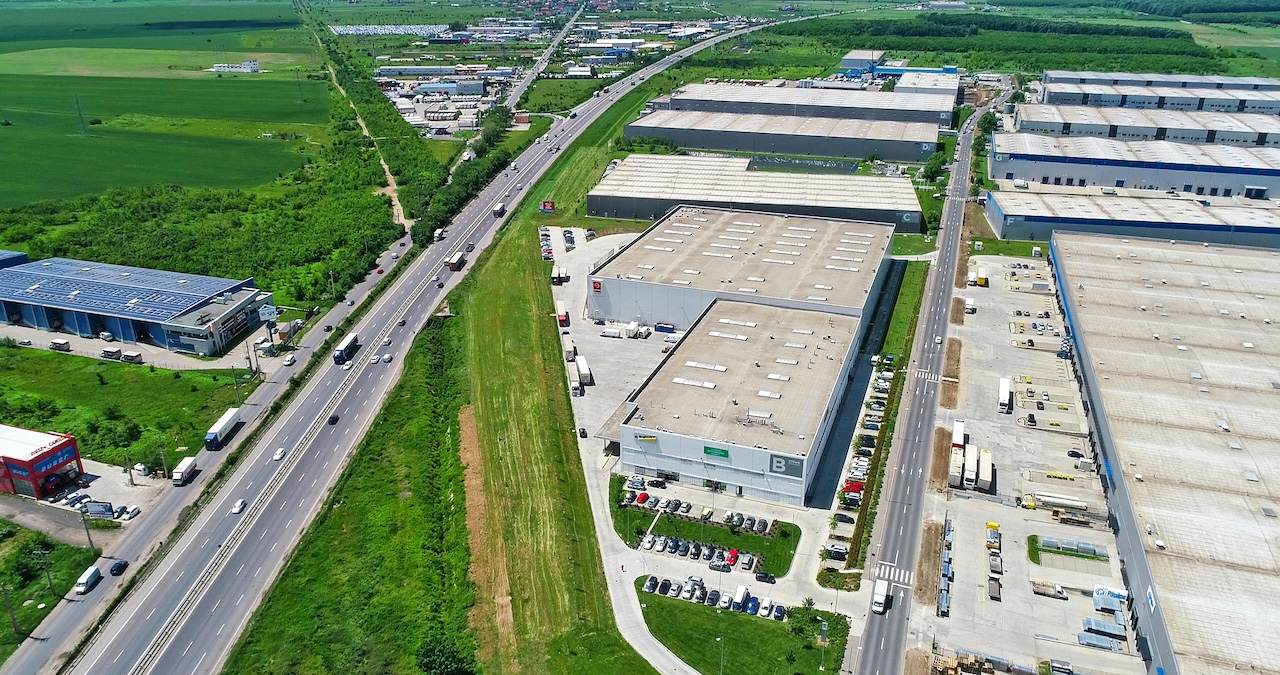
AMPIP Adds 40 Industrial Parks in Mexico: How Much Will Be Invested and How Many Jobs Will Be Generated?
Oct 22, 2026
Tequila: Why Was It Cheaper to Toast in September?
Oct 8, 2026
Consumer Confidence Drops in September 2026, INEGI Reveals
Oct 6, 2026
German Company Mankiewicz to Generate How Many Jobs in Querétaro?
Oct 28, 2026